In end-October, global fund managers were writing gloomy newspaper articles on why FPIs (Foreign Portfolio Investors) were getting very pessimistic about India. If the government didn’t do something about this soon (like remove capital gains tax on equities), they said, the Indian market risked becoming irrelevant.
Investors we pitched our PMS to echoed these thoughts – “I’m not feeling very positive about India right now. I’ll hold off until the FPI sentiment gets better.”
But that waiting has entailed an opportunity loss. Even as those articles were being written, FPI sentiment was turning. Pausing their net selling of Indian stocks from the middle of October, FPIs turned aggressive buyers in November. Indian stocks received $8 billion in net FPI inflows between mid-October and November 10th. As a result, the Nifty50 has gained 13% in a month and the rupee has appreciated by 3% against the USD.
What explains this turn of events? Why did FPIs leave India and what made them return? It is important to understand this, to guide better decisions in future.
Why FPIs sold
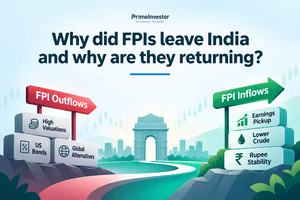
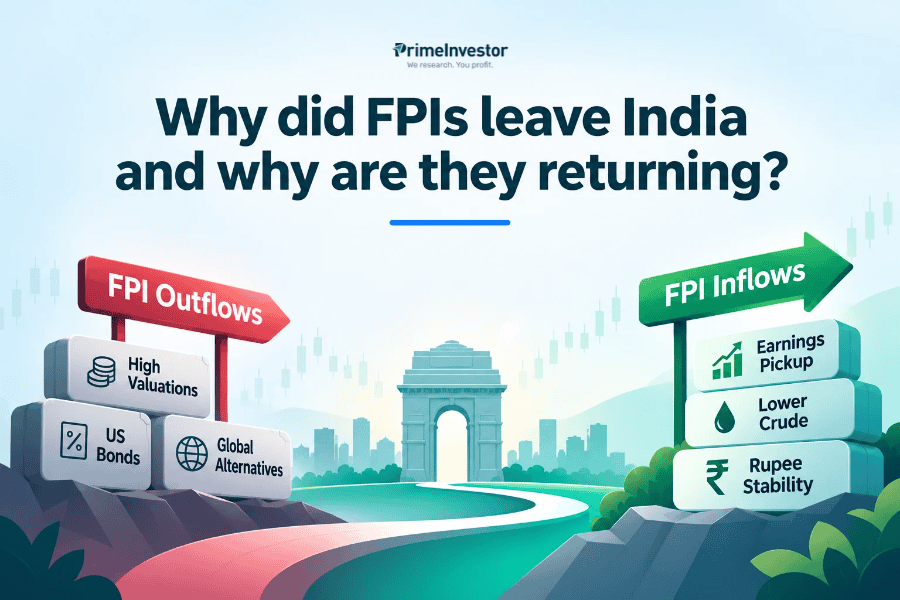
When FPIs net sold Indian stocks for two years from October 2024 to October 2026, there were many explanations offered. The common ones were:
- FPIs are put off by India’s high valuations relative to other emerging markets
- They are worried about the Iran war hitting India’s trade deficit and the Rupee
- They are vexed with the lack of innovation and capex in Indian companies
- They prefer US bonds after the spike in treasury yields
- They are unwinding Yen carry trades because of non-zero rates in Japan
- They are frustrated with India’s low returns and Rupee depreciation
- They prefer South Korea, Taiwan, etc., which are delivering much better earnings growth than India due to semiconductors, chips, etc.
- They prefer to bet on the global AI trade in which India plays no part
In the last month, only some of the above risk factors for India have diminished.
- With Democrats taking both Houses in the US mid-terms, the war in Iran seems to be de-escalating
- Brent crude has dipped below $100/barrel
- The Democrats want to slow the AI buildout. This has forced markets to reassess if the scorching growth for hardware suppliers to AI (based in South Korea, Taiwan and Japan) will slow
- As AI hyper-scalers and infrastructure companies rely more on bond markets to bankroll their buildout, lenders are turning wary about payoffs
- RBI’s FCNR scheme has brought in a bounty of USD and stemmed Rupee depreciation. Rate hikes by India’s MPC have also helped
But the other factors working against India remain. Indian companies continue to be stingy about R&D. Japanese and US bond yields remain juicy for global investors. India is still absent from the AI capex buildout. So why are FPIs now ‘returning’ to India despite these minuses?
Explaining FPI actions – A slippery slope
The real answer is that FPIs did not ‘leave’ India en masse until October. Nor have they returned in hordes in November. To understand recent FPI actions, their behaviour needs to be looked at through the following lens.
# 1 Not one class
FPIs are not a uniform class of investors who get vexed with a country and desert it. Nor do they suddenly develop a fondness for a country they hated just the week before. At any given point in time, some foreign investors have a negative view on the Indian market and are selling out of it, while others have a positive view and are buying or holding it. The FPI numbers we see are the net result of these opposing actions.
Today, over 12,200 FPIs are registered with SEBI to invest in Indian markets. These comprise foreign sovereign wealth funds, pension funds, global index funds, actively managed funds, hedge funds, university endowments, charities, banks, insurers, portfolio managers, corporate entities and individuals. Each of these investors clearly has a different investment objective, horizon and level of access to other markets.
A hedge fund following an absolute return strategy may ditch Indian stocks for Japanese or US treasuries when the rupee is depreciating. But an emerging market equity fund cannot move from Indian stocks to buy Japanese bonds – it can only move on to other emerging markets say Brazil or South Africa. This is why on any given day or month, some FPIs are buying Indian equities and others are selling them. If the buying is more than the selling, we get net inflows.
Therefore, for FPIs to ‘return’ to India, all that is needed is a change in sentiment at the margin. This time round, a pickup in earnings growth in India seems to have coincided with a spike in worries about an AI capex bubble.
With US hyper-scalers, South Korean chip makers, Taiwanese and Japanese semiconductor and hardware stocks all correcting together, FPIs probably looked around for a hedge. India, with no AI participation, may have looked like a good bet to some FPIs, because of its still-healthy growth.
# 2 They don’t leave or return en masse
The NSDL data shows that between September 2019 and September 2024, FPI assets invested in Indian equities rose from Rs 28 lakh crore to about Rs 78 lakh crore. Between October 2024 and October 2026, they net sold about Rs 5.6 lakh crore in stocks or about 7% of their original holdings. They still retained 93% of their Indian holdings. But because FPIs are large players in the Indian market, their sales do trigger sharp price falls. Therefore, the value of remaining assets that FPIs held in India dipped from Rs 78 lakh crore in September 2024 to Rs 65 lakh crore by October 2026.
Despite considerable selling, FPIs retained significant stakes in India, suggesting that not all of them were bearish about India.
# 3 Hard to predict
FPIs are a diverse set of investors with differing views. Therefore, knowing what FPIs as a class are thinking about India is close to impossible. In their recent articles, global fund managers said that the FPIs they interacted with were pessimistic about India. They expressed concern that this negativity could create a vicious cycle of a weakening Rupee and falling capital flows. These articles were widely circulated as ‘evidence’ of everything that is wrong with India – capital gains tax, lack of innovation, lack of infrastructure, income inequalities etc.
But given the actual composition of FPIs, it is not possible for any single fund manager to know what all 12,200 FPIs are thinking about India. Therefore, when we read about FPI sentiment being bullish or bearish, we need to take it with a pinch of salt. What is more useful is knowing whether a sample of large global funds (which represent one section of FPIs) are under-weight or over-weight on India. A recent Jefferies report, after surveying 70 large emerging market funds, found 61% of them under-weight on India. This is actually a contrarian indicator which should make us bullish about India, as those weights can change anytime.
# 4 It’s not us, it’s them
Recent narratives about why FPIs were selling out of India wallow in self-criticism. They imply that FPIs are deserting India because of its high valuations, poor infrastructure, lack of AI play, income inequalities etc. But often, FPIs sell out of one market and buy another simply because it looks relatively better (just like we may sell one perfectly good stock and buy another). Net selling by FPIs for a spell does not mean that something is drastically wrong with India as a country or market.
As domestic investors, we should invest in Indian equities after assessing if the economy is in good shape and the companies we’re picking are delivering good growth.
To make this assessment, it is better to invest in a market and currency which you understand well. When the floor falls out of a stock in a market like Brazil or South Korea, we, as Indians, don’t have access to sufficient information to gauge whether this is an over-reaction to an event or a justified reversal.
What really happened
Looking at data on net FPI flows into Indian stocks, relative to earnings growth and valuations, the following seems to be the explanation for their actions.
- FPIs (some of them) may have begun selling out of India in October 2024, because with the Nifty50 PE at over 24, Indian stock valuations had moved into a historically high premium over other EMs.
- This was also a period when earnings growth for Indian companies began to slow. As the AI capex trade took wing globally, other markets such as the US, South Korea and Taiwan began to deliver strong earnings growth while trading at a lower PE.
- The Iran war in February 2026 brought up the added risk of an oil shock to India’s import bill and earnings, with surging oil prices sinking the Rupee.
It was perhaps this combination of high valuations, weakening earnings growth and emerging risks to that growth, which saw some FPIs (not all) sell India and seek greener pastures elsewhere.
By October 2026, Indian valuations had corrected to 20 PE and worries began to surface about whether growth in AI-driven stocks would slow. This likely made Indian markets relatively attractive again to some FPIs. The pickup in earnings growth here probably added to the appeal. What’s more, despite the Iran war, India’s macro indicators have consistently shown both the economy and corporate earnings remaining resilient to the oil shock. India’s current account deficit was contained at 0.5% of GDP in Q1FY27. The government is on track to stick to the fiscal deficit target of 4.3%. India’s debt-GDP is far below advanced economies and its GDP has been steadily printing 7-8% growth. Nifty50 and Nifty500 earnings growth are back to 15-20%.
What’s going for India
Returning growth apart, recent global events have also highlighted other positive features of the Indian stock market compared to other Asian markets and EMs.
- Unlike Taiwan or South Korea which are concentrated bets on a handful of semiconductor or hardware companies, India’s listed universe is a diversified bet on many sectors.
- India’s growth story is largely domestically driven. It is not disrupted by tariffs, trade policy changes or bubble bursts in other countries.
- India has a tightly regulated capital market which is not easy to manipulate. Thanks to rising domestic participation, Indian institutions now own a near 20% stake in Indian listed companies while FPIs own 15%, making for high and diverse institutional participation. The recent case of MSCI downgrading Indonesia and removing the market from its EM index because of suspected index-level manipulation highlights the importance of such regulation.
- Amid macro worries about other economies, India has managed its government finances very well since Covid. Its debt-to-GDP ratio is well below 100% and sovereign bond yields trade well within historical ranges. Today, global investors in countries ranging from Japan to France and US are worried about surging bond yields pressuring the fisc. Recently, Brazil’s bellwether stock index lost 14% in a single day and its currency plunged 8%, after an election result favouring its socialist party dashed hopes of fiscal reform. Election results or other events in India seldom provoke such extreme reactions.
- With direct retail ownership of equities at about 10% and domestic institutions owning a larger slice of the public float than FPIs, the Indian market now has the ability to absorb FPI selling without falling through the floor. Some market gurus have painted SIP flows as ‘dumb money’ and critiqued retail investors for ‘giving exit’ to FPIs.
However, there’s nothing dumb about regularly allocating a part of your savings to equities in a country where companies are delivering 10-15% earnings growth. But for the domestic participation, the Rs 5.6 lakh crore of FPI selling in the last two years would have triggered far more than the 15% correction in the Nifty that we experienced. When FPIs invest in a market, they do look for the ability to liquidate their holdings without regulatory curbs or high impact costs.
Takeaways
Overall, the takeaways for investors from recent FPI actions are as follows:
- The net FPI buying or selling we see is the result of differing actions by many different classes of FPIs. It doesn’t represent a single view on India or its market
- The overall FPI mood or the reasons for it cannot be gauged. Only sample surveys are possible on whether active funds are overweight or underweight on India.
- As FPI actions can be driven by the smallest of changes in any asset or country across the world, tracking those events to gauge how Indian stocks will perform is futile.
- If Indian companies can deliver consistent earnings growth and market valuations price that growth correctly, long-term FPIs will buy Indian stocks. Fund flows from short-term investors like hedge funds are entirely unpredictable. So, it’s hard to say if recent FPI buying will continue, ebb or accelerate.
Therefore, if you’re investing in Indian stocks as a domestic investor, the only metric worth tracking is the growth in the Indian economy and whether that is translating into earnings growth for listed companies. Everything else is a waste of time!